A rental property can be a strong wealth-building asset but may become less efficient over time. The issue is not always performance on paper. It is often the gap between the property’s equity, the net income it produces, and the amount of oversight it requires.
Transitioning from residential to NNN commercial real estate investing gives you a way to evaluate that gap. By moving from a residential rental into a commercial property with a triple net lease structure, you can keep real estate in your portfolio while reducing routine landlord responsibilities.
In many NNN properties, the tenant pays rent along with property expenses such as taxes, insurance, and maintenance, depending on the lease terms. This guide explains how the transition works and what you should review before finalizing the move.
Read more: NNN vs. Residential rentals: Which investment strategy creates better long-term wealth?
Step 1: Understand what changes when you move from residential to NNN
The transition from residential rentals to NNN commercial real estate changes the owner’s role.
Residential rentals often involve shorter lease cycles, tenant communication, and vacancy planning. Owners may also need to coordinate maintenance, unit turns, and rent adjustments. Even with third-party property management, owners still make decisions about repairs, capital improvements, pricing, and long-term hold strategy.
Triple net commercial real estate shifts the investment focus toward the lease and tenant. In a typical triple net lease, the tenant pays base rent plus property expenses such as real estate taxes, insurance, and maintenance. The exact responsibility depends on the lease language, so the document matters more than the label.
Step 2: Compare your current rental property against your income goals
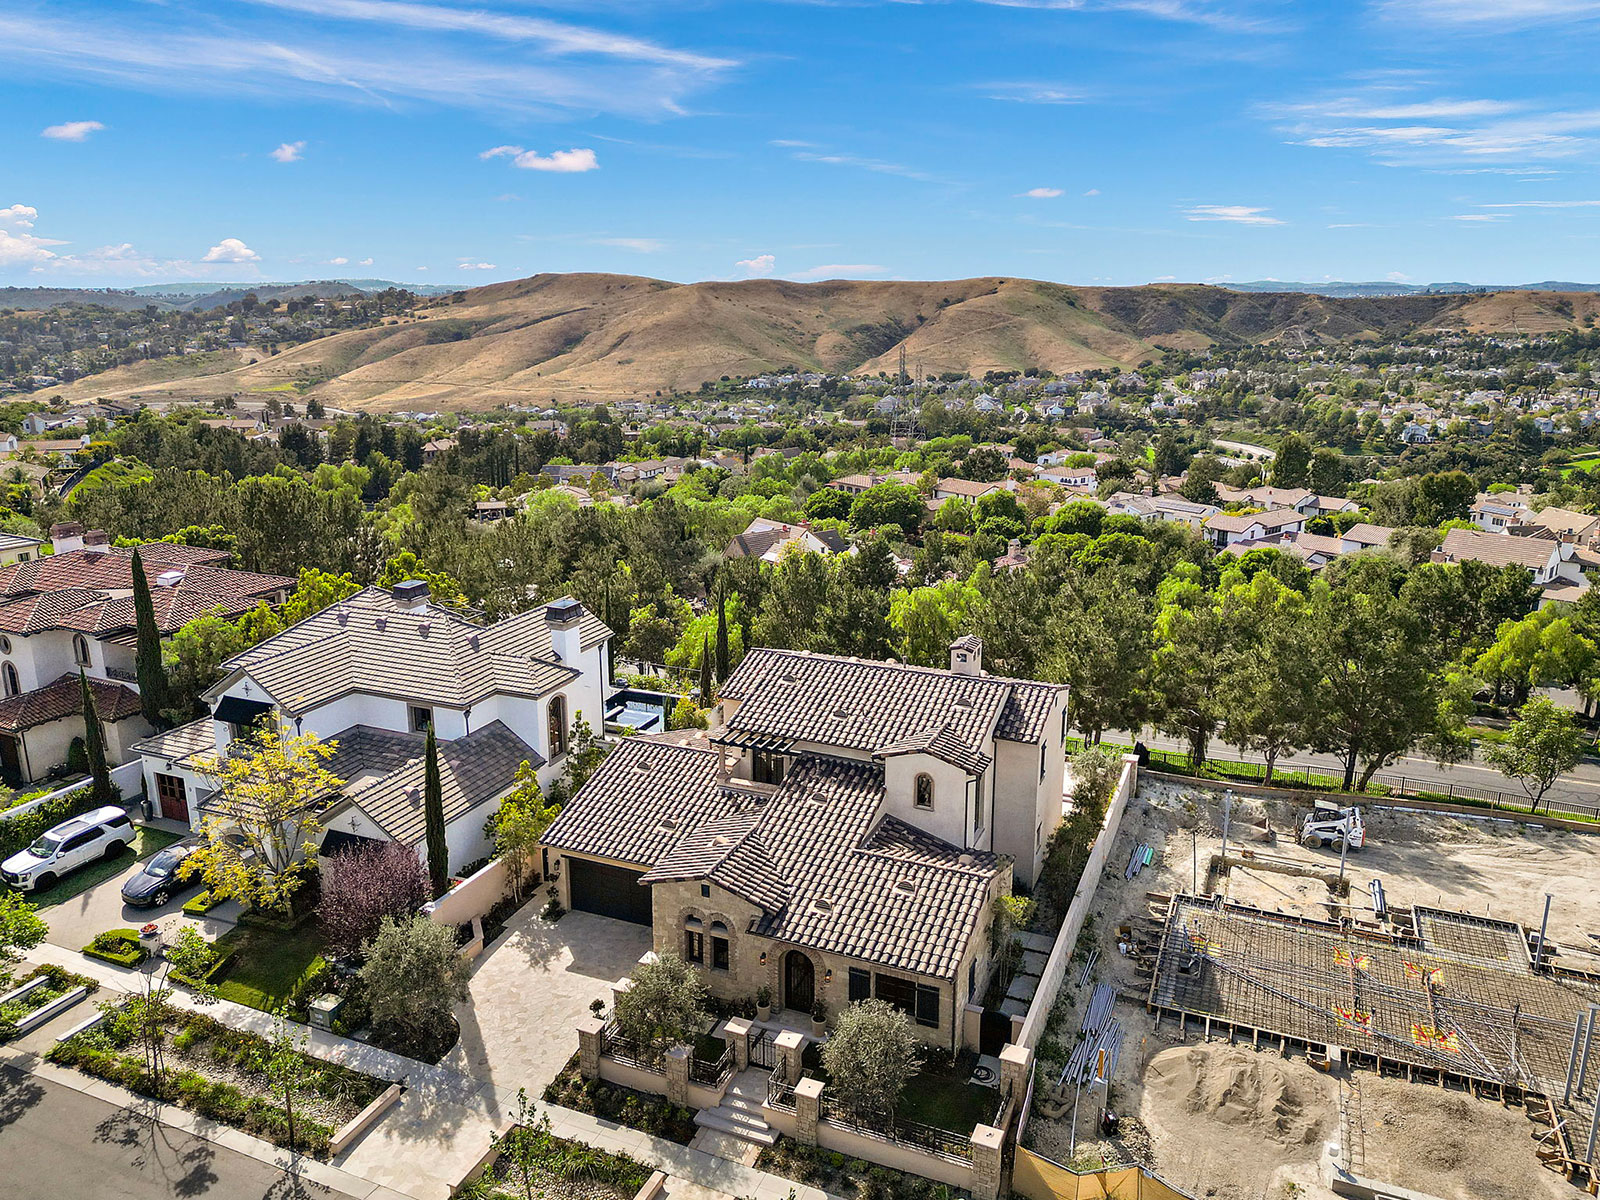
A rental property can build equity over time, especially in markets such as Orange County and Los Angeles County. The harder question is whether the property still produces the right income for your current goals.
Rental owners often begin evaluating residential to NNN commercial real estate investing when they face:
- Low net income compared with property value
- Tenant turnover and short lease terms
- Ongoing repair or capital expense exposure
- Rising insurance, tax, or maintenance costs
- Management fatigue
- A desire for more predictable retirement income
A useful review of the transition looks at net income, vacancy history, repair patterns, debt service, remaining equity, and the owner’s desired level of involvement for both the residential rental and the NNN replacement.
Step 3: Learn how triple net leases work
Triple net (NNN) investments are built around a lease structure where the tenant typically takes on more property-level expense responsibility than a residential tenant. In a standard NNN lease, the tenant usually pays base rent and also covers the three “nets”: property taxes, building insurance, and maintenance.
This structure can make income more predictable because fewer operating expenses flow back to the owner, and lease terms often run longer than residential leases.
NNN investments require a different type of review. The owner’s focus shifts to:
- Tenant credit
- Lease duration
- Rent increases
- Guaranties
- Location strength
- Building condition
- Re-leasing potential
A strong lease can reduce routine oversight. A weak lease can leave the owner with more responsibility than expected. That is why every NNN opportunity should be evaluated through the lease document, tenant profile, and physical condition of the property.
Step 4: Know the types of NNN properties and lease structures
NNN properties can include several commercial asset types, such as:
- Single-tenant retail buildings
- Medical or pharmacy properties
- Quick-service restaurants
- Automotive service properties
- Convenience stores
- Industrial assets
Lease formats vary. A gross lease may leave most operating expenses with the landlord, while a modified gross lease may split some expenses between landlord and tenant. A double net lease usually passes through two major expense categories. A triple net lease typically passes through taxes, insurance, and maintenance. An absolute NNN lease may place broader responsibility on the tenant, depending on the lease terms.
For investors, a careful lease review should confirm who pays for specific items such as:
- Roof repairs
- Parking lot work
- Structural issues
- Insurance
- Property taxes
- Common area maintenance
- Capital expenses
Step 5: Evaluate the investment beyond the cap rate
A cap rate, or capitalization rate, is a common way to compare income-producing properties. It generally measures a property’s annual net operating income as a percentage of its purchase price.
A higher cap rate may offer more income, but it may also reflect tenant risk, a short lease term, a weaker location, or upcoming expense exposure. A lower cap rate may reflect stronger tenant credit, a longer lease, or more investor demand.
Before choosing an NNN replacement property, you should compare:
- Net cash flow after debt service
- Lease term remaining
- Tenant credit profile and guaranty strength
- Rent increases during the lease
- Location quality and access
- Building condition and repair obligations
- Exit strategy and re-leasing potential
The replacement property should support your target income, time commitment, and risk profile.
Step 6: Understand where a 1031 exchange may fit
A 1031 exchange may allow you to sell qualifying investment real estate and acquire a like-kind real property while generally deferring gain recognition. The IRS states that Section 1031 now applies only to exchanges of real property, and the property must be held for business or investment use rather than primarily for sale.
For residential rental owners, like-kind does not mean identical. The IRS generally treats real properties as like-kind when they share the same nature or character, even if they differ in grade or quality.
This means a residential rental held for investment may potentially be exchanged into commercial investment real estate, including an NNN property, if the transaction meets Section 1031 requirements.
Timing is one of the biggest planning issues. In a deferred exchange, replacement property generally must be identified within 45 days, and the replacement property must generally be received within 180 days or by the tax return due date, including extensions, whichever comes earlier.
Read more: 1031 Exchange explained: How to turn your rental property into passive income
Step 7: Review the risks before choosing a replacement property
NNN properties can reduce management responsibilities, but they still require careful review. The main risks usually involve the tenant, lease, building, location, and exchange timeline.
Tenant strength affects rent reliability and future resale. Lease terms determine which expenses stay with the owner, including roof, structure, parking lot, and capital costs. Location affects re-leasing potential if the tenant leaves.
Exchange deadlines can also create pressure. Starting the replacement search early gives investors more time to compare properties instead of reacting to the 45-day or 180-day timeline.
Step 8: Build a transition plan
A practical transition starts with a review of your current rental property’s income, equity, debt, tenant status, and likely sale proceeds. The sale strategy should also account for pricing, access, lease terms, buyer expectations, and timing.
The NNN replacement search should begin early, especially if a 1031 exchange is involved. Investors can then compare income, lease structure, tenant strength, location, and building obligations before deadlines create pressure.
A well-organized transition usually includes:
- Reviewing the current rental property’s income, equity, debt, and repair exposure
- Preparing the residential asset for sale
- Estimating net proceeds and possible 1031 exchange requirements
- Starting the NNN replacement search before the sale closes
- Comparing tenant quality, lease terms, income stability, and property obligations
- Coordinating the sale, due diligence, exchange, and closing
The Accruvia Group approach
Accruvia Group focuses on one specific transition: helping residential investment owners sell rental properties and reinvest into commercial NNN properties. Many professionals handle either the residential sale or the commercial acquisition. Accruvia Group helps clients evaluate and coordinate both.
As a real estate investment advisor, Accruvia Group reviews the current rental property’s income, equity, and management burden, then compares NNN opportunities based on lease terms, tenant quality, income stability, location fundamentals, and long-term fit. For owners tired of tenant management and inconsistent income, the goal is a more structured move into commercial real estate income with fewer routine obligations.
Learn more about the Accruvia Group approach here.
FAQs about transitioning into NNN investments
Are NNN commercial properties truly passive?
NNN properties are generally more passive than residential rentals, but owners still monitor lease compliance, tenant performance, insurance, taxes, and lease expiration dates.
Can a residential rental be exchanged into an NNN commercial property?
Yes. A residential rental held for investment may potentially be exchanged into commercial investment real estate through a 1031 exchange, if the transaction meets the applicable requirements.
Do NNN properties appreciate like residential rentals?
NNN properties can appreciate, but value is often tied to income, lease terms, tenant quality, cap rates, and location fundamentals. Residential values may rely more on comparable sales and local housing demand.
Moving from active ownership to structured income
Transitioning from residential rentals into NNN properties can help owners stay invested in real estate while reducing the day-to-day work often tied to residential ownership.
Accruvia Group helps clients throughout Orange County and Los Angeles County evaluate residential sale options, review NNN investment opportunities, and coordinate the steps involved in moving from active landlord responsibilities to a more passive commercial real estate structure.
Call 949-679-2340 or send an email to discuss your rental property transition.